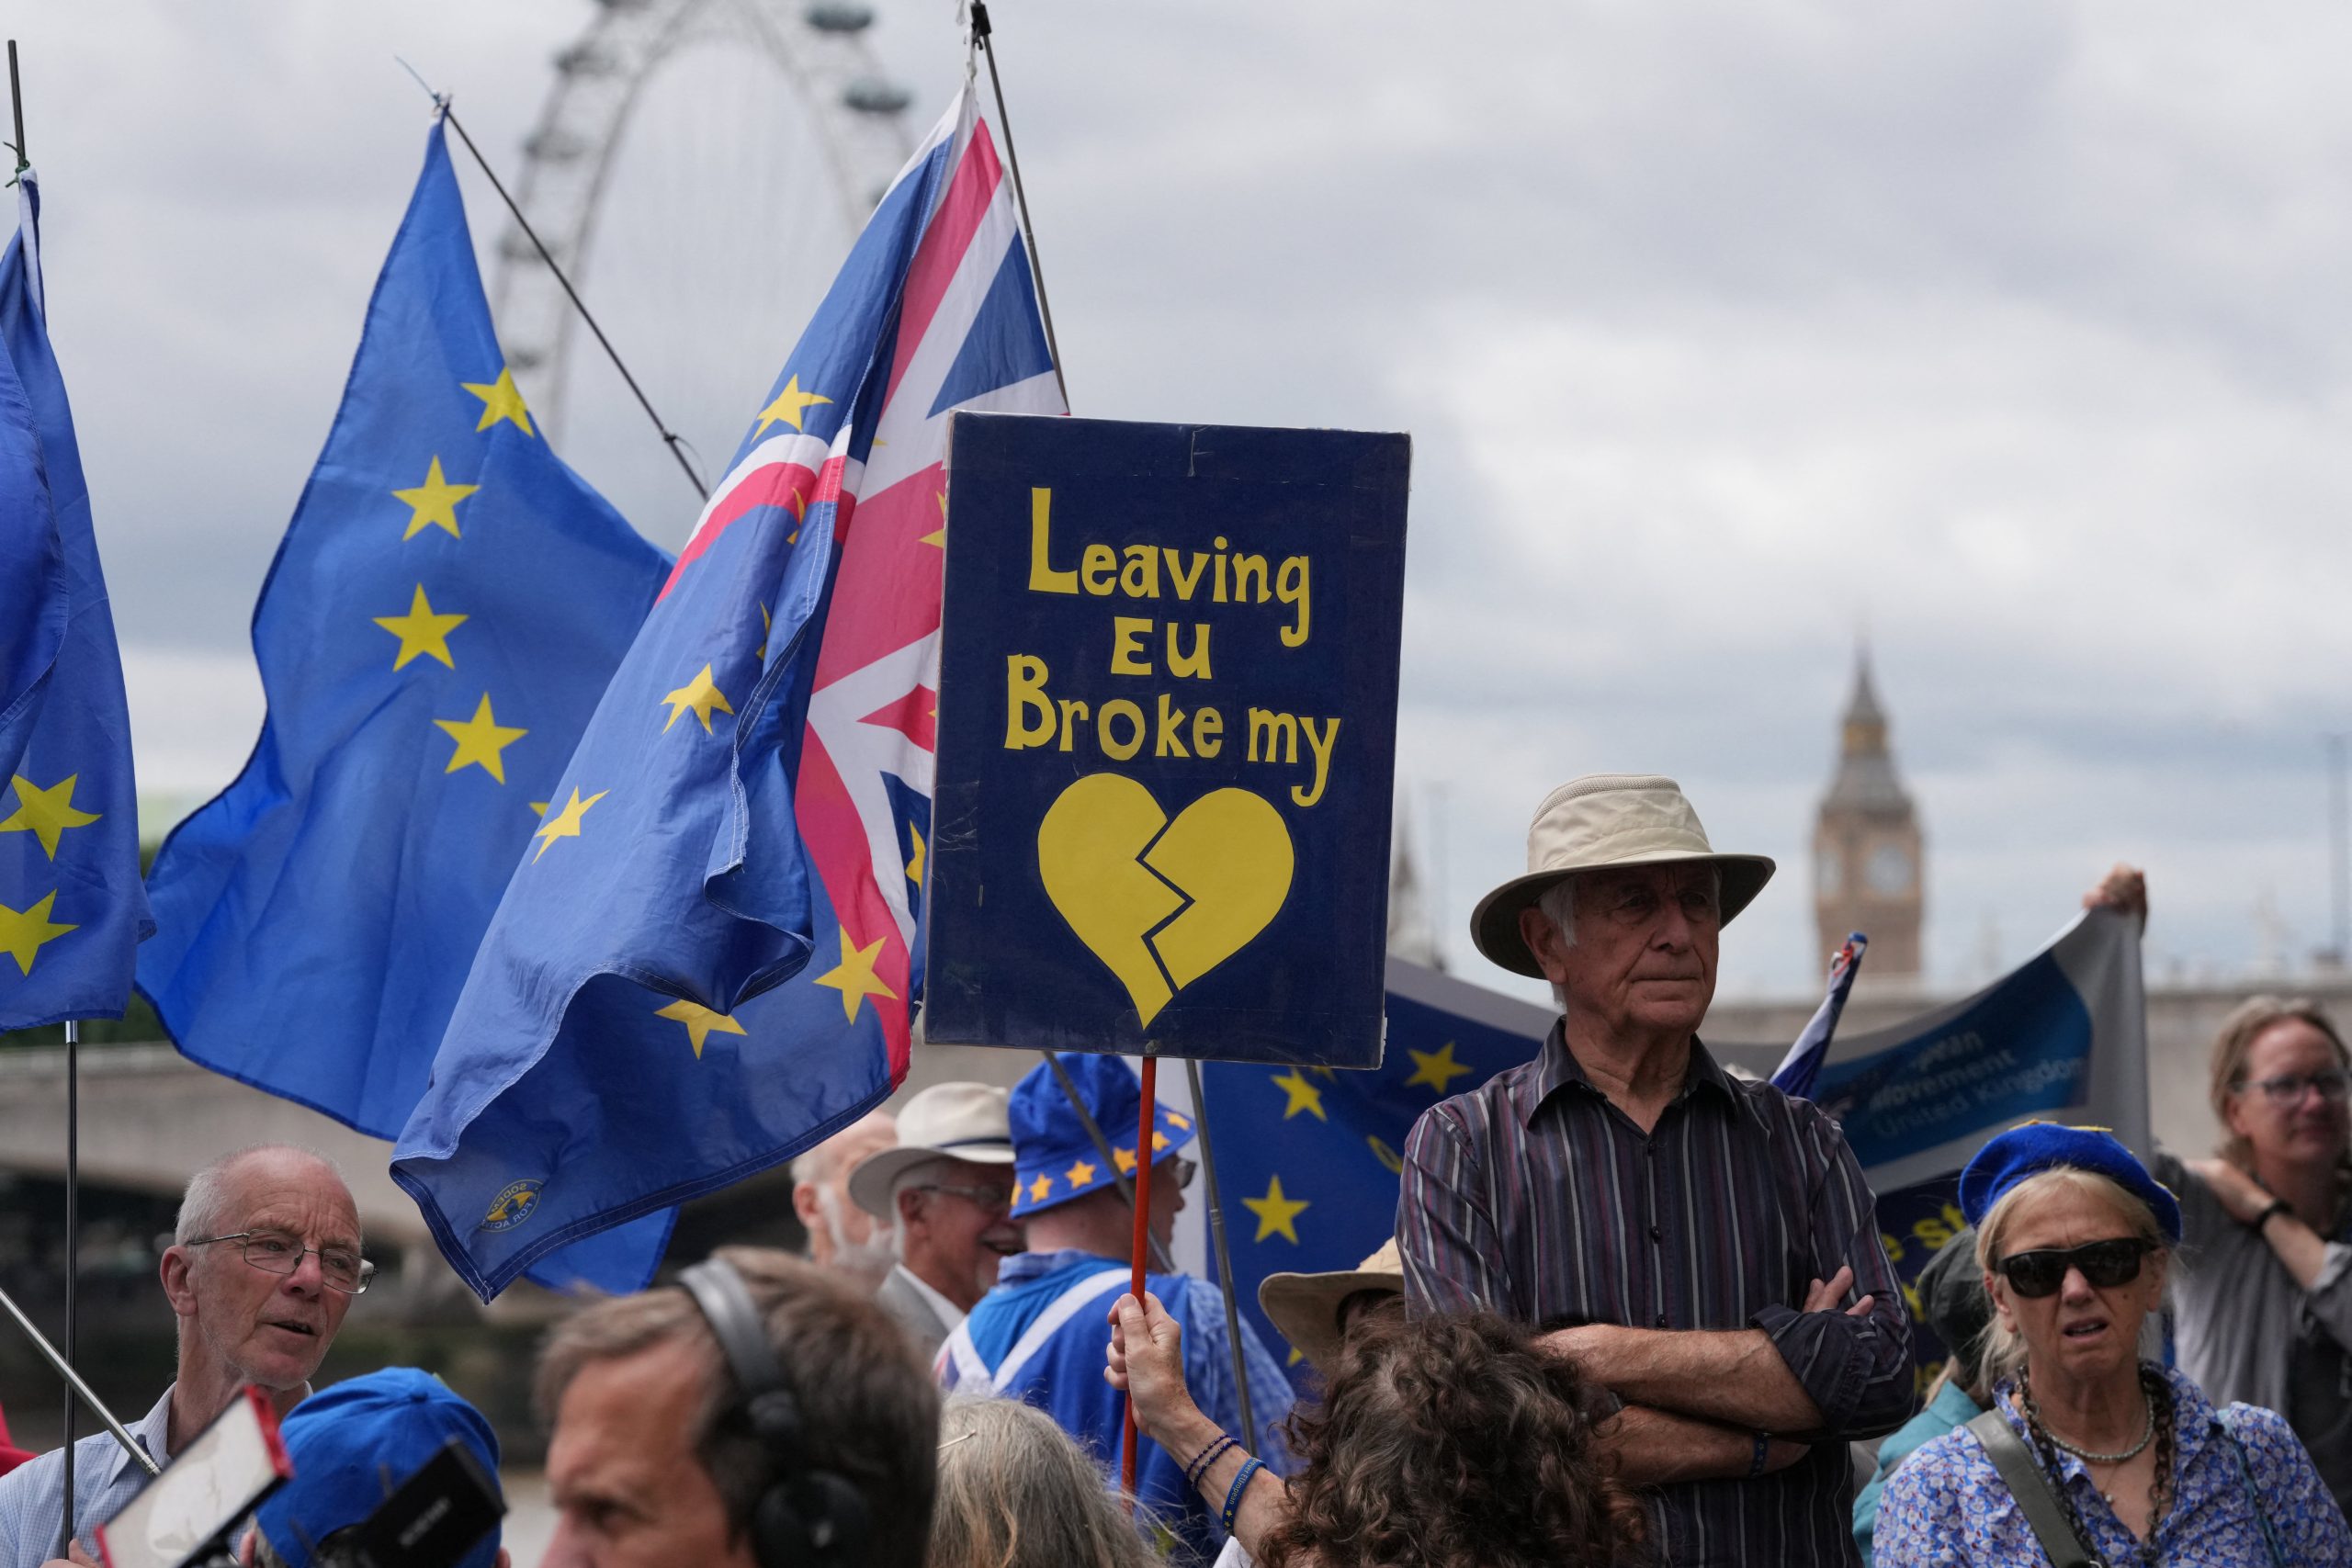
Ten years ago, Britain voted to leave the European Union and, looking back at the extraordinary arguments surrounding that decision, it is worth asking a straightforward question: was Brexit worth it?
I remember the arguments well. We were going to take back control of our borders, our laws and our money, while Britain would emerge as a buccaneering global trading nation, liberated from the bureaucracy of Brussels and free to strike deals around the world.
On the other side, we were warned of recession, rising unemployment, collapsing house prices and businesses fleeing Britain. George Osborne, one of the loudest voices making those warnings in 2016, just posted last week in The Economist that Britain has “fallen off a cliff” since leaving Europe.
So, who was right?
The answer is more complicated than either side would probably like because Britain did not collapse after Brexit, but neither did it experience the economic liberation that many of Brexit's strongest advocates promised.
There was no immediate recession after the referendum, unemployment did not explode and the City of London did not relocate to Frankfurt. London remains one of the world's great financial centres and the more apocalyptic predictions made during the referendum campaign proved exaggerated.
That does not make Brexit an economic success because its costs have emerged more gradually through trade, investment and productivity. The Office for Budget Responsibility has long assumed that Brexit will leave UK productivity around 4% lower in the long term than it would have been inside the European Union, while other studies estimate an even larger effect.
Trade is an obvious part of this. The European Union remains Britain's biggest trading partner, accounting for around 41% of UK exports and almost half of imports in 2025, but British companies now face customs and regulatory barriers that did not exist inside the single market. Each piece of friction may look small, but put millions of transactions together and they create a significant economic drag.
Services have done much better, which matters because Britain is predominantly a services economy.
London remains a financial powerhouse and British technology and fintech companies continue to innovate, but investment is more troubling because we cannot see the factory built in France rather than Britain, the European headquarters placed in Amsterdam rather than London or the investment that went somewhere else because access to the European market was easier.
Then there is immigration, where the Brexit story becomes particularly interesting.
Taking back control of Britain's borders was central to the Leave campaign and Brexit delivered that control by ending freedom of movement. Yet net migration subsequently rose dramatically, while its composition shifted away from Europe towards the rest of the world.
Meanwhile, “stop the boats” became a defining political slogan as successive governments struggled with small-boat crossings of the English Channel. Legal migration and asylum seekers arriving by small boats are very different issues and should not be confused, but politically they collide with the same Brexit promise: Britain would control its borders.
This exposes the difference between sovereignty and outcomes. Brexit gave Britain control over immigration policy, but British governments decided how to use that control, while managing irregular migration still requires cooperation with France and other European countries. Taking back control therefore also meant taking back responsibility.
That brings us to the strongest argument in favour of Brexit: sovereignty.
Britain gained greater freedom over immigration, trade and regulation and, in areas such as fintech, digital assets, artificial intelligence and financial services, that should offer opportunities to move faster than a European Union that has to find agreement among 27 countries.
The frustrating part is how little Britain appears to have exploited that freedom.
There is also a practical constraint because regulatory divergence sounds attractive until a British company discovers that it must comply with British rules at home and European rules to sell into its largest overseas market. The more Britain diverges, the more sovereignty it exercises, but the more friction it risks creating.
Which brings me to the question at the heart of Brexit ten years later: what exactly did we buy?
We bought sovereignty, greater control over immigration policy, independent trade policy and regulatory freedom. If those were your reasons for voting Leave, Brexit delivered much of what you wanted.
If you expected Brexit to make Britain richer, the evidence is far less convincing.
We should also recognise that this was hardly a normal decade. Britain went through Covid, Russia's invasion of Ukraine, an energy shock, soaring inflation, rapidly rising interest rates and extraordinary political instability, making it difficult to separate Brexit from everything else that happened.
Since the referendum, Britain has had seven Prime Ministers and a revolving door at the Treasury, hardly suggesting the political stability that investors like. Meanwhile, Britain's cost of borrowing has risen sharply, with ten-year gilt yields recently exceeding 5% and reaching levels not seen since before the global financial crisis. It would be wrong to blame that on Brexit alone, as inflation, government finances, geopolitical shocks and global bond markets all play their part, but it forms part of a decade in which Britain's reputation for economic and political stability has taken a battering.
Nevertheless, after ten years the evidence increasingly points in the same direction: Brexit has weakened trade, investment and economic output relative to where Britain would probably have been. So, was it worth it? That depends upon something economists cannot calculate: how much is sovereignty worth?
If greater national control over laws, borders, regulation and trade is worth sacrificing some economic prosperity, Brexit may have been a price worth paying. If prosperity and easier access to Britain's largest market matter more, the bargain looks considerably less attractive.
That is why arguing about whether Brexit “worked” misses the central point. Brexit was an exchange in which Britain surrendered some economic integration and, according to the evidence, some prosperity in return for greater sovereignty and political autonomy. Whether that was a good exchange depends upon what you value most.
What makes the next ten years interesting is that Britain appears to be moving closer to Europe again, without seriously proposing to rejoin the European Union. A closer relationship over trade, security, defence and regulation could recover some of the benefits of European integration while preserving much of the political independence Brexit delivered.
Maybe that is where Brexit eventually settles because, after a decade spent arguing about whether Britain should be in Europe or out of Europe, we may rediscover something geography has been telling us all along.
Britain is an island with its own history and political identity, but it is an island just twenty-one miles from France.
We can leave the European Union, determine our own laws and decide our own political future, but we cannot vote to change geography … even with the Bayeux Tapestry.
If you want more opinions, click here:
https://www.bbc.co.uk/news/articles/cdrynjz1glpo
https://www.bbc.co.uk/news/articles/cyv0m164m84o
https://www.instituteforgovernment.org.uk/comment/brexit-10-economy
https://ukandeu.ac.uk/brexit-ten-years-on-the-economy/
https://www.theguardian.com/politics/2026/jun/14/how-uk-economy-changed-since-brexit-vote-charts
Chris M Skinner
Chris Skinner is best known as an independent commentator on the financial markets through his blog, TheFinanser.com, as author of the bestselling book Digital Bank, and Chair of the European networking forum the Financial Services Club. He has been voted one of the most influential people in banking by The Financial Brand (as well as one of the best blogs), a FinTech Titan (Next Bank), one of the Fintech Leaders you need to follow (City AM, Deluxe and Jax Finance), as well as one of the Top 40 most influential people in financial technology by the Wall Street Journal's Financial News. To learn more click here...