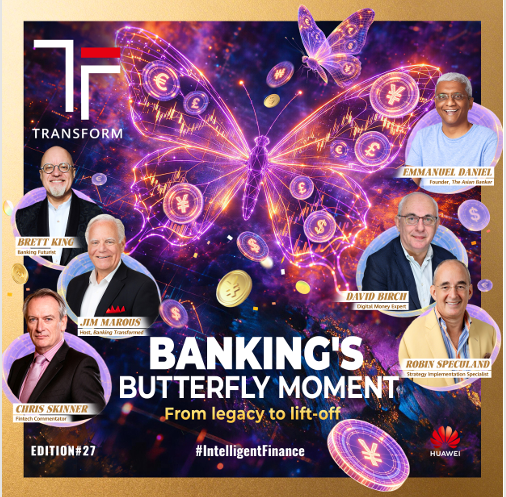
I asked AI to summarise the latest edition of Huawei’s financial magazine called Transform, and this is what it came back with. I think AI is not objective …
Transform Issue 27: Banking’s Butterfly Moment
The most striking contribution in Huawei’s Transform Issue 27 comes from Chris Skinner, who argues that banking is moving beyond digitalisation into something fundamentally different: the intelligent bank. His argument is not that banks need to add AI to their existing systems, but that they need to rebuild the technological foundations of banking around AI. The magazine summarises his challenge neatly: AI agents will anticipate customer needs and manage money on their behalf, but making that possible requires a technological overhaul. The editor describes Skinner’s prescription as “Herculean but unavoidable”: the infrastructure of the bank needs to be founded on an AI-native platform capable of understanding and anticipating customer needs.
Skinner draws a sharp distinction between a bank that is doing digital and one that is genuinely AI-native. Digital banking essentially took the old banking model and put it onto screens. Intelligent banking changes the model itself. The bank needs an infrastructure capable of continuously understanding and predictively modelling what customers need, rather than waiting for them to open an app, select a product and initiate a transaction. His example is Ant Group, which, he notes, was already working on its fifth technology architecture only twelve years after launch, effectively rebuilding every three or four years. By contrast, many European and American banks are still carrying systems deeply embedded over decades.
His definition of an intelligent bank is wonderfully simple: customers no longer need to think about money or finance. AI agents do that for them. The bank observes, anticipates and acts, only involving the customer when a decision or warning genuinely requires attention. The examples are practical rather than science fiction: the bank recognises that someone buying individual public-transport tickets would save money with an annual pass, but also knows they lack enough cash to buy one, so it proactively offers the financing required to make the saving. Tomorrow's AI agent could make even that decision for the customer.
That leads Skinner to what is probably the biggest idea in his contribution: bot-to-bot banking. Customers will delegate financial authority to personal AI agents, those agents will communicate with the bank's agents, and much of what we currently regard as banking will happen between machines. That radically changes responsibility and trust. If a bank's agent transfers money to a fraudulent agent, who is liable? Skinner argues that the bank cannot simply blame the machine. If customers have trusted the institution and its intelligent agents to act properly, responsibility remains with the bank.
There is an important qualification to all of this. Skinner does not argue that AI removes the need for banking. Quite the opposite. He argues that we will continue to need financial intermediation because we need trust and security, although the intermediary increasingly does not need to be human. He even sees a continuing role for physical branches, not necessarily for transactions or advice but as visible manifestations of trust. He cites Italian challenger CheBanca!, whose founder told him branches were about “trust and marketing”; locations with a physical presence attracted substantially more deposits and assets than locations without one.
That argument fits remarkably well with the rest of the edition. The magazine's overarching thesis is that finance is approaching what it calls “banking's moment of lift-off”: AI takes banking beyond digital access and towards intelligent assistance, while execution determines which institutions turn that technology into genuine customer value.
Brett King approaches the same destination from another direction. He argues that banks must become technology companies that happen to provide financial services, rather than banks with technology departments. Eventually banking becomes an “invisible layer” of infrastructure in which payments, transfers and routine decisions simply happen. The differentiator becomes how well the institution understands and responds to the customer, encapsulated in his phrase “Utility equals trust.” King also identifies the prerequisite that repeatedly appears throughout the magazine: banks cannot deliver meaningful AI without unified customer data. Fragmented data produces fragmented intelligence.
Jim Marous makes the customer argument even more forcefully. Most banks, he says, are asking how AI can reduce costs when the strategic question is how AI can deepen customer relationships and create revenue. Banks already possess extraordinary amounts of information about customers but rarely act upon it because data remains trapped in silos and institutions are often more interested in avoiding risk than managing it. His challenge to banks is wonderfully direct: “If you're a bank, you need to show you know me.”
David Birch then turns the argument around. The biggest disruption isn't that banks are getting AI; customers are getting AI. Personal agents won't get bored comparing savings rates, insurance policies, mortgages and pensions. They will continuously optimise financial choices that humans currently neglect because doing so is tedious. That threatens some highly profitable banking behaviours, particularly inert deposits earning little or no interest. It also means banks increasingly compete not for human attention but for selection by the customer's AI. The report therefore moves naturally from artificial intelligence towards digital identity and verifiable credentials, because banks need to know that the agent requesting a transaction genuinely has authority to act for that customer.
Emmanuel Daniel provides the necessary warning. Once autonomous agents begin making decisions and interacting with other autonomous agents, the governance structure of banking itself has to change. Errors can propagate from agent to agent until it becomes difficult even to determine where they originated. Banks therefore need new accountability mechanisms, monitoring and clearly defined “kill switches”. His central question is not whether AI will occasionally fail, but what happens when it does and who remains responsible.
The statistics at the beginning of the magazine show why this matters now. 81% of financial-services firms report some AI adoption, but only 14% describe it as transformative; 52% have agentic-AI pilots or deployments underway, while only 24% regard autonomous-agent deployment as achieved today. That last number is expected to reach 81% by 2030. At the same time, 72% of AI vendors identify data quality and completeness as a deployment problem and 46% cite legacy systems and siloed data.
Oh, and there is also me old mate Robin Speculand. If you don't know Robin, then you missed a trick as he knows more about Asia, DBS and change management than most people.
Put together, the edition tells a coherent story. Skinner says rebuild the bank around AI. King says become a technology company. Marous says use the intelligence to understand the customer rather than merely cut costs. Birch says prepare for customers themselves to become AI-enabled. Daniel says work out who is accountable when autonomous systems act. The common thread is that AI is not another channel comparable with mobile or internet banking. It changes who makes the decision, when the decision is made and, eventually, whether the customer consciously interacts with the bank at all.
Download the magazine here: transform-issue27-final.pdf
Chris M Skinner
Chris Skinner is best known as an independent commentator on the financial markets through his blog, TheFinanser.com, as author of the bestselling book Digital Bank, and Chair of the European networking forum the Financial Services Club. He has been voted one of the most influential people in banking by The Financial Brand (as well as one of the best blogs), a FinTech Titan (Next Bank), one of the Fintech Leaders you need to follow (City AM, Deluxe and Jax Finance), as well as one of the Top 40 most influential people in financial technology by the Wall Street Journal's Financial News. To learn more click here...