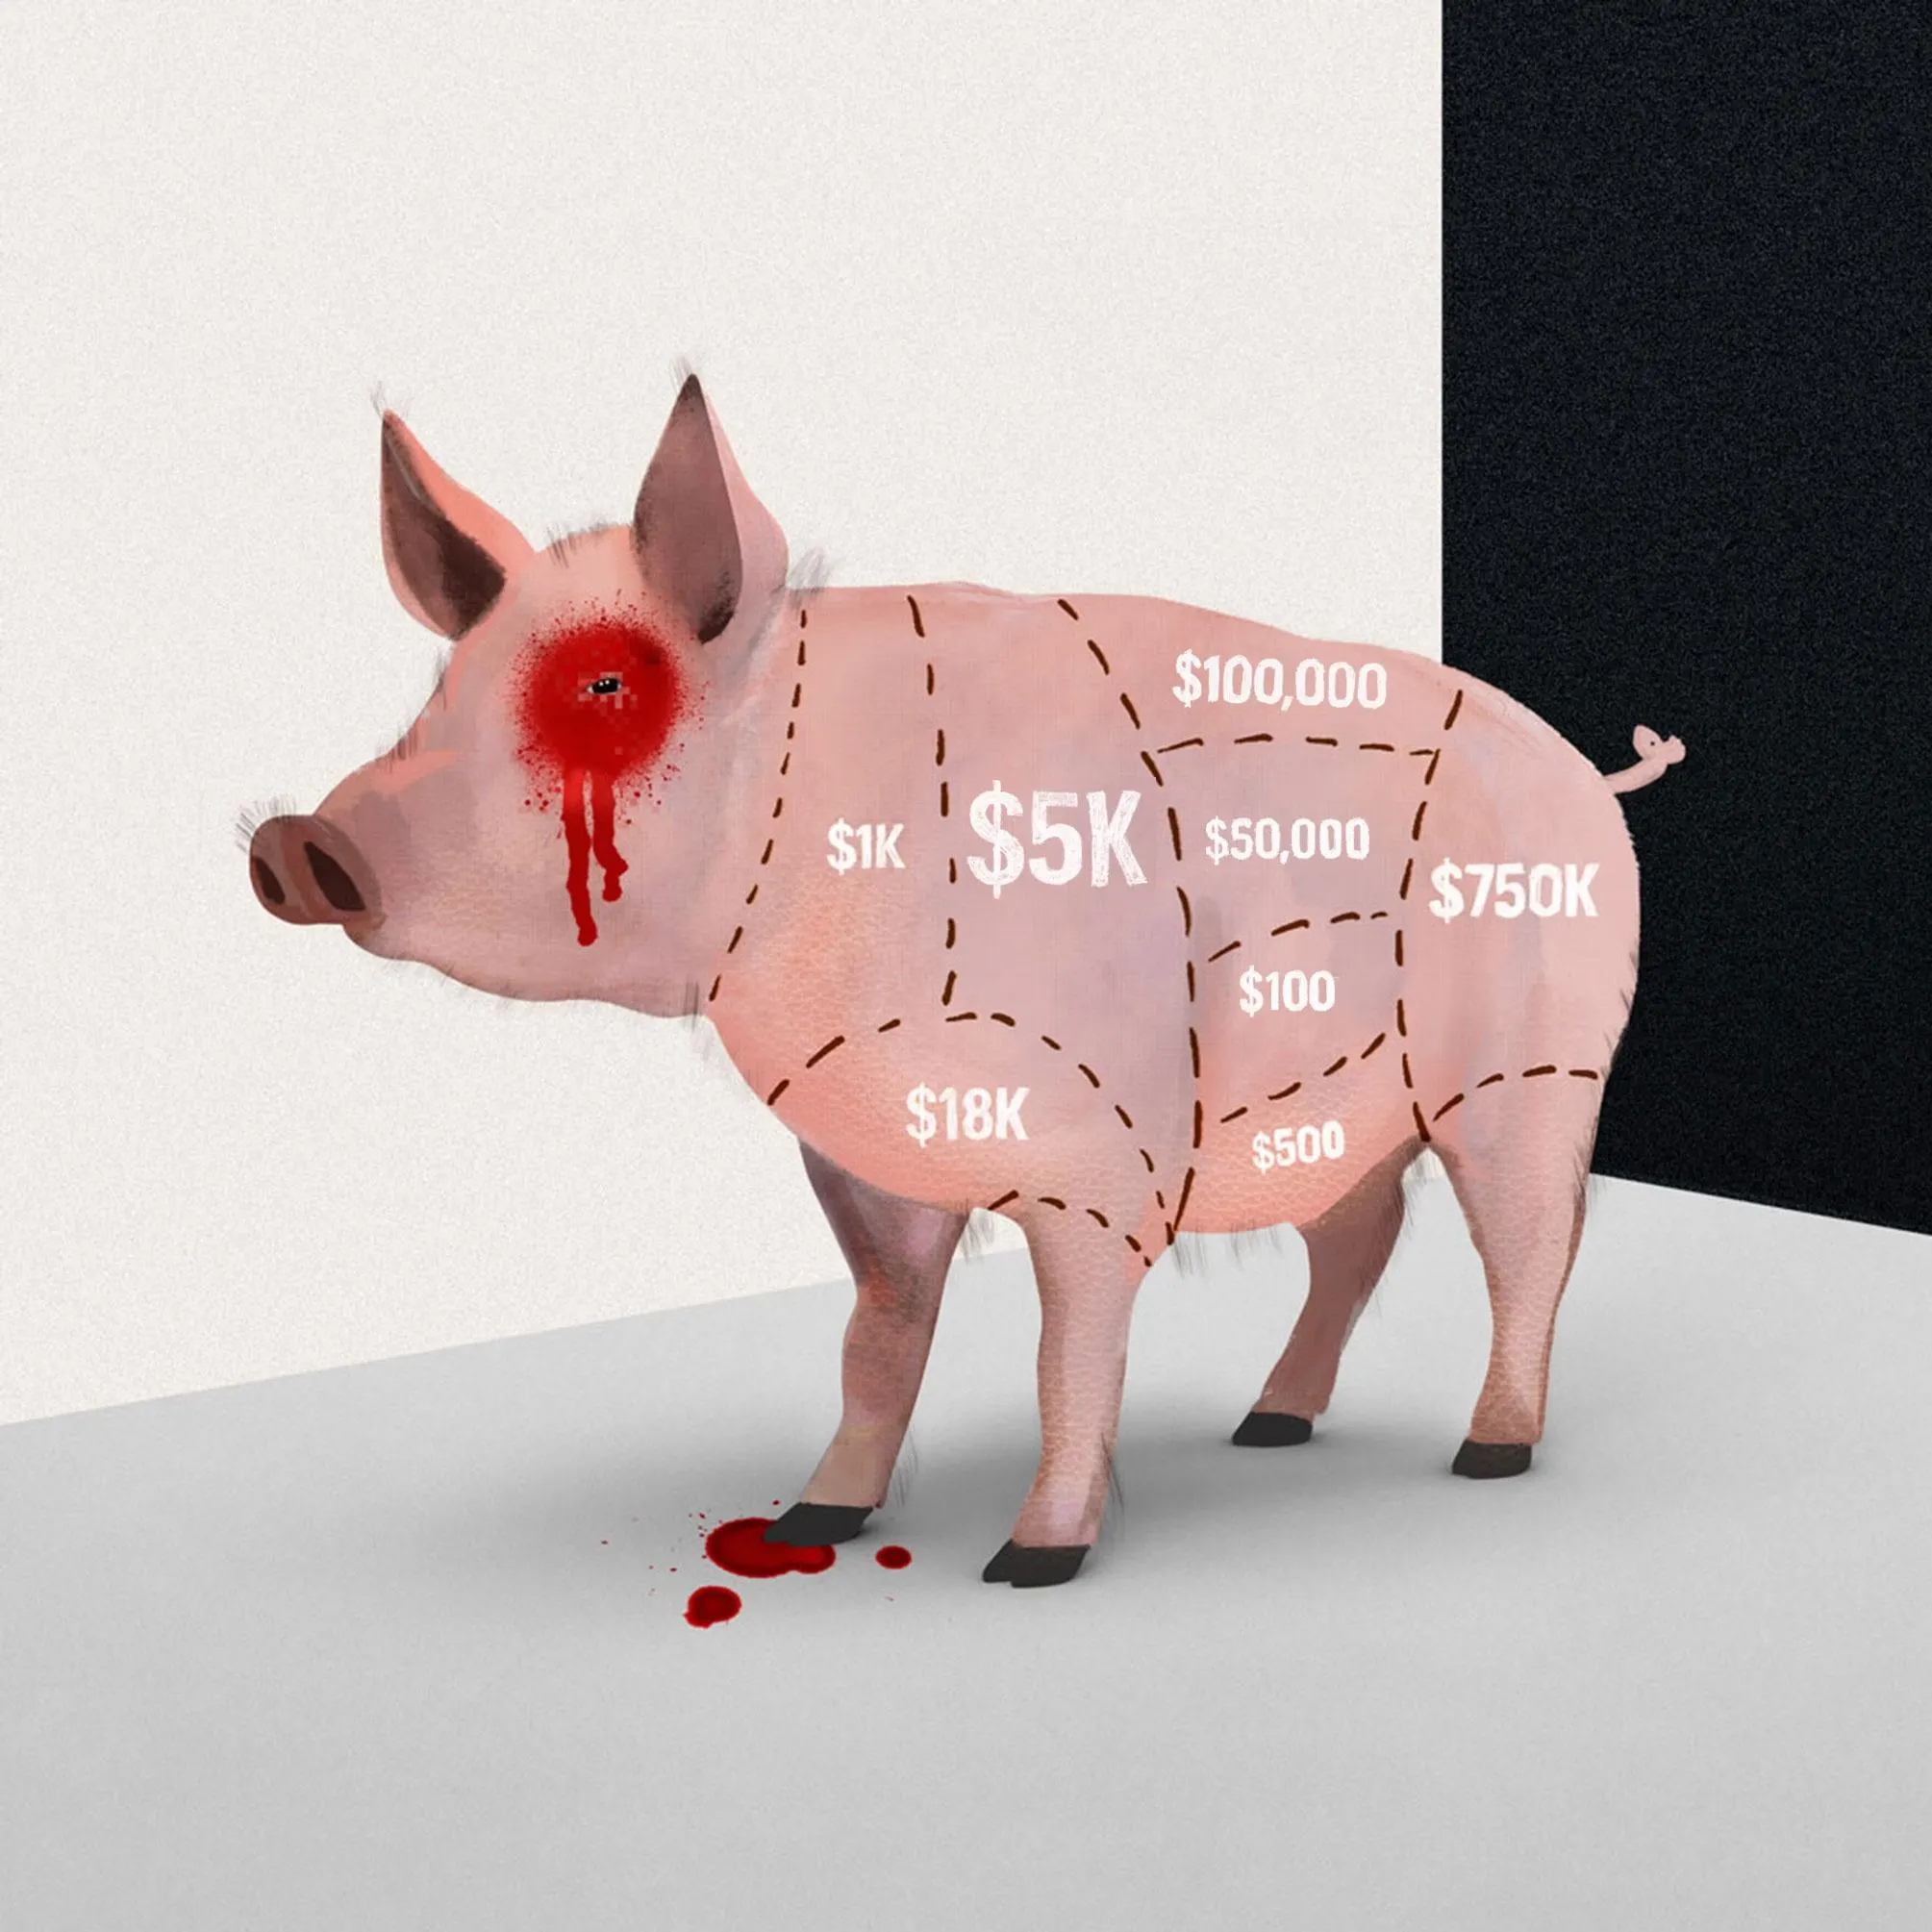
Pig-butchering crypto scams are a serious and growing problem in St. Louis, Missouri, and across the United States. The FBI's Internet Crime Complaint Center (IC3) reported that Americans lost $9.3 billion to cryptocurrency-related fraud in 2024, marking a 66% increase from the prior year. Pig butchering schemes accounted for roughly $5.8 billion of those losses. In Missouri, consumers reported more than $88 million in total fraud losses in 2023, according to FTC data. These scams can wipe out savings through staged affection, false trust, and fabricated investment screens. Stolen assets often move across wallets within minutes, then pass through exchanges or mixers.
First things first, what is a pig-butchering scam?
A pig butchering scam is a long-term financial fraud where criminals build fake online relationships with victims over weeks or months before tricking them into investing in fraudulent cryptocurrency or trading platforms. Some would call them romance scams, but it goes further, and recovery may be possible but timing, records, and reporting carry real weight.
For victims exploring pig butchering scam recovery options with qualified legal counsel can be a critical first step. Banks, investigators, law enforcement, and civil claims can create practical routes toward recovering lost assets. A calm, documented response gives victims the best chance to protect what remains as a strong file starts with proof, not assumptions. Save every chat, transfer receipt, wallet address, transaction hash, exchange notice, and screenshot before accounts disappear. Lawyers assessing pig butchering scam recovery often compare payment routes with platform claims, account openings, romantic scripts, and withdrawal demands. Organised records give investigators names, dates, amounts, technical markers, and communication patterns they can test against blockchain data with less delay.
Then you need to know that timing matters.
Confirmed crypto transfers cannot be reversed like card charges. Early reporting still matters when assets reach a regulated exchange or bank-linked account. Victims should contact their bank, card provider, crypto platform, and local police as soon as fraud becomes clear. Quick action may freeze exposed accounts, limit further loss, and create a dated record for later review.
Then you need to report the scam.
Several reports may be useful because no single agency controls every part of the case. A police report gives victims an official record. If you’re an American, a complaint to the Federal Bureau of Investigation can help agents connect related schemes. The SEC has also flagged investment scams tied to cryptocurrency as a growing threat to investors. Reports to the Federal Trade Commission support consumer fraud tracking. Exchanges may ask for case numbers before reviewing suspicious wallet activity.
You should also contact financial institutions.
Banks may help when wires, cards, checks, or automated payments funded the scheme. Some transfers can be recalled if staff receive notice fast enough. Card chargebacks may apply to limited payment types. Even when money cannot be returned, financial institutions can close exposed accounts, monitor unusual activity, and reduce the risk of repeat withdrawals.
Meanwhile, if you transferred cryptocurrencies then, if assets passed through a known exchange, victims should report wallet addresses, transaction hashes, and account details. Compliance teams may freeze accounts tied to suspected theft. They often request identification, police reports, and transfer records. An exchange may need legal process before releasing funds, yet a freeze can preserve assets before they leave the platform.
Blockchain tracing can also help. Many blockchains leave public records that can be analysed. Tracing may show where assets moved, which wallets received them, and whether money entered an exchange. This work does not promise repayment. It can, however, give law enforcement, lawyers, and compliance teams evidence for subpoenas, freeze requests, or broader investigations.
Civil claims can also apply.
Some victims may have claims against scammers, money mules, fake platforms, or parties that helped move funds. Lawsuits can seek damages, account records, and asset restraints. Results depend on identity, jurisdiction, proof, and available property. Civil action can be costly, so victims should compare likely recovery with fees, time, and stress.
Critically, people need to beware of recovery scams.
Fraud groups often target victims again after the first loss. They may pose as hackers, agents, investigators, or crypto specialists. Upfront fees, guaranteed refunds, and secret methods are warning signs. Legitimate professionals explain costs, limits, contracts, and expected steps. No honest provider can promise full repayment from anonymous wallets.
And, moreover, tax issues matter.
Crypto fraud may affect tax filings, but the rules are narrow and fact-sensitive. Victims should consult a qualified tax professional before claiming any loss. Records should show dates, amounts, wallet addresses, payment sources, and messages tied to each transfer. Tax treatment may depend on theft rules, investment activity, or personal payment history.
Emotional pressure is also part of the scheme.
These scams often build trust through long conversations, affection, urgency, and social pressure before asking for money. Victims may feel shame, anger, fear, or disbelief after discovering the fraud. Those reactions are common. Responsibility belongs with the criminals who built the trap. Support from family, counsellors, or victim groups can help people make steadier decisions.
So, what to do after a loss?
Victims should change passwords, enable stronger account security, and scan devices for remote access tools. Credit freezes may help if personal details were shared. New messages from unknown contacts deserve caution. Fraud groups may reuse phone numbers, photos, and private facts. A written safety checklist can reduce panic and prevent rushed transfers.
In conclusion, victims can recover money after a pig butchering crypto scam, but no outcome is certain. Stronger cases usually involve fast reporting, detailed records, traceable transfers, and assets that reached a regulated platform. Legal action, exchange reviews, bank recalls, and law enforcement support may each matter. The priority is stopping further loss, then building a careful record that gives recovery efforts a fair chance.
Chris M Skinner
Chris Skinner is best known as an independent commentator on the financial markets through his blog, TheFinanser.com, as author of the bestselling book Digital Bank, and Chair of the European networking forum the Financial Services Club. He has been voted one of the most influential people in banking by The Financial Brand (as well as one of the best blogs), a FinTech Titan (Next Bank), one of the Fintech Leaders you need to follow (City AM, Deluxe and Jax Finance), as well as one of the Top 40 most influential people in financial technology by the Wall Street Journal's Financial News. To learn more click here...