Revolut’s Nik Storonsky doesn’t want to run a bank
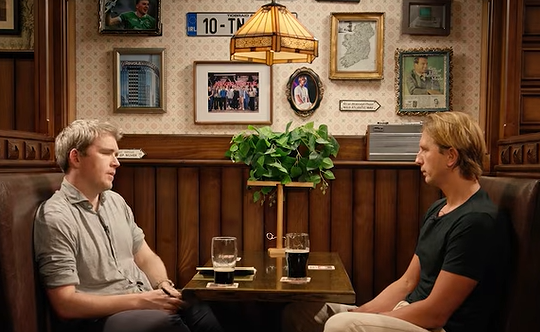
When the founder of one of the world’s fastest-growing digital banks explains how he runs his business, you might expect a conversation about banking strategy, regulation, risk management and financial performance. Instead, you get a discussion about product development, artificial intelligence, customer behaviour and why traditional banking is such a poor business model. Oh and all over a pint in the pub.
That was my overriding impression from a recent conversation between Revolut founder Nik Storonsky and Stripe co-founder John Collison on the Cheeky Pint podcast.
It is a revealing discussion, not least because Storonsky appears remarkably uninterested in following the conventions of banking. Revolut has reached around 80 million customers, attracting approximately 100,000 new customers daily, and is preparing to challenge American Express and JPMorgan Chase in their home market according to its founder, Nik. Yet the philosophy behind its growth is strikingly different from that of most established banks.
In fact, listening to Storonsky, I was left with a question. What if the greatest threat to traditional banks isn’t a better bank, but a company that doesn’t want to behave like a bank at all?
A good example is given in one of the most revealing parts of the conversation when John and Nik talk about lending. Traditional banks make much of their money by taking deposits, extending credit and earning the difference between funding costs and lending income. It is the foundation of banking profitability and has been for centuries, but Storonsky doesn’t like it.
His argument is that lending creates a fundamentally unpredictable business.
Banks can generate substantial profits for years, only to see those profits disappear when unemployment rises, borrowers default and credit provisions increase. He compares lending economics to selling options, collecting premiums during good times while remaining exposed to potentially severe losses during bad times.
Instead, Revolut wants to emphasise transactional income, subscriptions and recurring customer revenues. Storonsky says his target is to keep lending below 10% of the balance sheet, with other lending exposures securitised.
That is a remarkable ambition for a banking business.
It also explains why Revolut is so interested in subscriptions.
A customer paying monthly for a premium account generates recurring revenue without creating the credit risk as a loan. Storonsky points to Revolut Ultra, a premium subscription costing around €50 a month, as an unexpectedly successful product.
There is another dimension to this strategy. Technology businesses traditionally attract higher earnings multiples than banks, reflecting their perceived growth potential and lower exposure to credit cycles. Storonsky explicitly recognises this distinction.
Of course, subscriptions are not risk-free. Customers cancel, competitors undercut prices and premium benefits cost money to provide. Equally, lending remains an essential economic function, and a bank that avoids it must find other ways to create value from its deposits and customer relationships.
Nevertheless, the strategic distinction is important. Revolut wants the customer relationship, transaction activity and financial ecosystem without becoming heavily dependent on the traditional economics of credit.
That is a very different vision of banking.
The second striking feature of Revolut is its approach to innovation.
Traditional banks tend to develop new products through lengthy business cases, committees, budget negotiations and multiyear transformation programmes. Revolut operates something closer to a technology laboratory.
Storonsky describes an internal process called “new bets”, where small teams are established to develop products. They receive funding, build their propositions and launch into selected markets. Performance is then compared with the historical results of roughly 100 previous experiments. Successful products receive more investment. Underperforming products lose resources, although Revolut maintains existing services where withdrawal would harm customers. The crucial distinction is that Revolut has developed a repeatable innovation process rather than treating each new product as a major strategic initiative.
Storonsky argues that most companies make too few bets and take too long to learn from their failures. Revolut, by contrast, has accumulated enough experience to identify what successful products look like during their early development.
There is a lesson here for established banks. Innovation isn’t just about having good ideas or employing talented people. It is about creating an organisation capable of testing ideas repeatedly, measuring results and reallocating resources without becoming emotionally attached to yesterday’s decisions.
Yet I would challenge one aspect of this philosophy. Not every valuable financial service produces immediate commercial returns. Trust, financial inclusion, customer protection and long-term infrastructure investment cannot always be judged against a twelve-month profit curve.
A bank must distinguish between products that can be experimented with and obligations that must endure.
That is where technology-company thinking encounters the realities of being a financial institution.
Perhaps the most consequential part of the interview concerns artificial intelligence.
Storonsky describes how Revolut initially introduced AI to improve customer support and translation, before extending it into engineering, marketing and other operational activities. The ambition now goes much further, towards creating what he calls an AI employee capable of completing work across an entire process.
He even suggests that a product development team that traditionally required eight or ten specialists could eventually operate with two people, as AI enables developers to work across front-end systems, back-end infrastructure and data science.
What makes this interesting is that Revolut hasn’t yet reorganised itself around this possibility. Storonsky acknowledges that its existing structures, permissions and specialised functions still prevent the company from exploiting AI’s full potential.
This is a critical observation.
Most banks are approaching AI by asking how it can make their existing processes more efficient. Storonsky is questioning whether those processes, and the organisational structures supporting them, should continue to exist at all.
That is the difference between automating a business and redesigning one.
However, a two-person development team is not the same as a two-person banking operation. Regulatory accountability, operational resilience, fraud prevention and customer protection remain demanding responsibilities, regardless of how much code an AI system can produce.
The challenge is to redesign the institution without weakening the safeguards that make it trustworthy.
The interviews moves on and discusses that fact that, despite its enormous customer base, Revolut faces a familiar banking problem. Having an account is not the same as using it as your main financial relationship.
Storonsky acknowledges that only around 10–20% of Revolut’s monthly active customers, depending on the country, receive their salaries into their accounts.
This matters because the primary account creates a much deeper relationship. Salary deposits lead to regular payments, savings, investments, subscriptions and additional financial services.
Revolut is therefore concentrating on converting occasional users into primary banking customers, while also developing products for children and younger consumers.
Storonsky claims Revolut has reached more than half of the under-35 population in many European markets, although this refers to having an account rather than using Revolut as their primary bank.
The distinction matters.
Traditional banks still control much of the wealth held by older generations, and customers remain reluctant to move their principal financial relationships. Revolut’s challenge is to convert youthful popularity into enduring financial relationships as those customers grow older and wealthier.
There is also an intriguing role for AI here. Revolut already uses machine learning and large language models to recommend products based on customer behaviour, transaction patterns and commercial relevance.
In effect, the bank is building an automated relationship manager.
The opportunity is enormous, but so is the question of whose interests such a system serves. Does it recommend the product that best meets the customer’s needs, or the one that generates the greatest profit for Revolut?
That distinction will become increasingly important as AI moves from supporting financial decisions to making them.
Storonsky is also clear about Revolut’s ambitions in the United States.
He wants to compete directly with premium credit card propositions from American Express and Chase, combining competitive rewards with Revolut’s wider ecosystem of banking, investments, trading and other financial services.
He says Revolut has received conditional approval for a US banking charter, with further approvals still required, and hopes to expand significantly during 2027.
This is a particularly interesting test of the company’s strategy.
Revolut succeeded in Europe partly because it entered markets where established banks offered expensive, cumbersome and outdated products. The United States is different. Premium credit cards are sophisticated, rewards programmes are deeply embedded in consumer behaviour and competition is intense.
Revolut will also have to demonstrate that its subscription-led, relatively low-credit-risk model can succeed in a market where credit is central to the economics of consumer banking.
The American market will be an important test of whether Revolut has built a genuinely transferable banking model or one particularly suited to European conditions.
One final observation from the conversation caught my attention.
Storonsky says he spends approximately 95% of his time internally, reviewing products, performance and business processes. He limits conference appearances to a handful each year and believes too many chief executives devote excessive attention to external activities.
His argument is that leadership means understanding the products and ensuring that the organisation delivers.
There is something refreshing about that, although I wouldn’t go as far as suggesting that bank CEOs should abandon external engagement. Relationships with regulators, governments, investors and customers are integral to running a financial institution.
Nevertheless, his broader point is difficult to dismiss.
How many banking executives spend more time discussing transformation than checking whether their products are genuinely better than those of their competitors? How many organisations celebrate innovation programmes without measuring whether those programmes create lasting customer value?
Revolut’s approach is uncompromising, heavily quantitative and relentlessly focused on execution. It is also demanding, and the conversation leaves open important questions about culture, sustainability and the balance between commercial performance and institutional responsibility.
Yet the central lesson is compelling.
For decades, banks have attempted to become technology companies by investing in technology. Revolut has approached the problem from the opposite direction, building a technology-driven organisation and progressively adding the capabilities, licences and responsibilities of a bank.
That doesn’t automatically make Revolut’s model superior. Banking involves obligations that cannot be reduced to product growth, customer acquisition or profitability, but it does expose a fundamental weakness in much of the industry’s transformation agenda.
Traditional banks keep asking how technology can improve banking. Revolut is asking how much of traditional banking needs to survive, and that is a far more uncomfortable question.
This is a summary based on Nik Storonsky’s interview with John Collison on Cheeky Pint, published 10 November 2026. Figures and strategic targets are attributed to Storonsky’s statements in the interview, rather than independently verified company disclosures. Read the full transcript or watch the interview.
And oh, if you want to truly understand Revolut's culture, click here: https://revolut.typeform.eu/philosophy
Chris M Skinner
Chris Skinner is best known as an independent commentator on the financial markets through his blog, TheFinanser.com, as author of the bestselling book Digital Bank, and Chair of the European networking forum the Financial Services Club. He has been voted one of the most influential people in banking by The Financial Brand (as well as one of the best blogs), a FinTech Titan (Next Bank), one of the Fintech Leaders you need to follow (City AM, Deluxe and Jax Finance), as well as one of the Top 40 most influential people in financial technology by the Wall Street Journal's Financial News. To learn more click here...