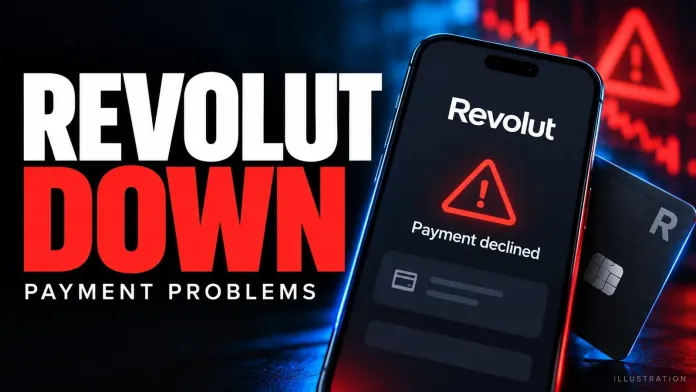
When Google Goes Down, Your Bank Goes Down. Who Is Really in Control?
We spent decades worrying about banks being too big to fail. Now we have a handful of technology companies that are too important to fail, and yesterday demonstrated why that should terrify us.
I’ve recently been blogging and writing about the dangers of concentration risk in cloud providers and the fact that just a few firms now run the infrastructure for global banking. This became prescient yesterday when Google Cloud suffered a major outage at its London data centre, and suddenly customers of some of Britain's biggest banks discovered that their money was inaccessible.
Revolut, Lloyds, Halifax and HSBC were among the financial institutions reporting disruptions. Customers struggled to access banking apps, make payments, transfer money and withdraw cash. Meanwhile, the disruption spread beyond banking to businesses, public services and even the technology used for court hearings.
The cause? Google reported a power event affecting its London cloud infrastructure.
Think about that.
We have spent billions building sophisticated financial systems, strengthening capital requirements, introducing liquidity rules, conducting stress tests and making sure that banks can withstand the next financial crisis. Yet a problem with the power supply at a technology company's data centre can leave millions of people wondering whether they can buy their morning coffee.
Welcome to the new systemic risk. It isn't sitting on a bank's balance sheet. It's sitting in someone else's data centre.
From too big to fail to too connected to fail was a recent series of blogs:
Too Intelligent to Fail (Part Two)
Too Digital to Fail (Part Four)
And now it has come true.
Remember the global financial crisis of 2008?
The fundamental problem was that financial institutions had become so interconnected that the failure of one threatened the survival of others. Lehman Brothers collapsed, confidence evaporated and the financial system nearly imploded because nobody knew who was exposed to whom.
The response was a decade of regulation designed to prevent another catastrophe. Banks were required to hold more capital, maintain stronger liquidity positions, understand their counterparty exposures and demonstrate that they could survive extreme financial shocks.
All sensible stuff, but while regulators were busy strengthening the financial system, something else was happening. Banks were moving their technology infrastructure into the cloud.
Amazon Web Services, Microsoft Azure and Google Cloud became the foundations of an increasingly digital financial system. Banks embraced them because cloud computing offered scalability, flexibility, faster innovation and access to technologies that would be extraordinarily expensive to develop independently.
The business case was compelling and still is. The problem is that when thousands of institutions outsource critical technology to a handful of providers, they don't eliminate risk. They concentrate it.
In 2008, banks were dangerously interconnected through financial exposures. In 2026, they are increasingly interconnected through technology dependencies.
The contagion mechanism has changed, but the underlying problem is remarkably familiar.
The illusion of diversification
Here's the uncomfortable question for every bank chief executive and chief risk officer. How diversified is your bank, really? You may have millions of customers, thousands of employees, operations across dozens of countries and a sophisticated risk management framework that measures everything from interest rate exposure to geopolitical instability. You may even have multiple data centres and extensive disaster recovery procedures … but what happens when your cloud provider fails? What happens when your payments processor depends on the same cloud provider? What happens when your identity verification service, fraud detection platform and customer communications systems all rely on infrastructure operated by the same handful of companies?
Suddenly, your carefully constructed diversification strategy starts looking rather less diversified.
Worse, even banks using different cloud providers may share dependencies through telecommunications networks, software libraries, identity services and specialist technology vendors.
This is the fundamental difference between institutional concentration risk and systemic concentration risk.
A bank examines its own exposures and concludes that its infrastructure is sufficiently resilient. Another bank conducts the same exercise and reaches the same conclusion. So does another, and another.
Individually, each institution may appear well protected. Collectively, the financial system becomes dependent on the same underlying infrastructure.
Everyone has diversified their own risk, but nobody has diversified the system.
That is the danger and there is another important distinction that yesterday's outage exposed.
We tend to think about banking failures in financial terms. A bank fails when it runs out of capital, loses liquidity or cannot meet its obligations, but what happens when a bank has plenty of capital, ample liquidity and perfectly healthy assets, yet its customers cannot access their money?
Revolut reassured customers that their money and data remained safe during the disruption. That was important, but it didn't solve the immediate problem for someone whose card was declined or who couldn't withdraw cash.
From the customer's perspective, the distinction between a bank that has lost their money and a bank that temporarily cannot give them access to it is rather academic when they are standing at a supermarket checkout.
Of course, an operational outage is not the same as a bank failure, and yesterday's disruption was not a financial crisis. But it demonstrates how operational failure can undermine confidence in an otherwise financially sound institution.
And confidence matters.
Imagine a more severe scenario in which a major cloud failure lasts not six hours but six days, affecting multiple banks, payment processors and financial market infrastructures simultaneously.
What happens to salaries, pensions, mortgages, securities settlements and corporate payments? What happens when businesses cannot pay suppliers and consumers cannot access their accounts? More importantly, what happens to public confidence when people discover that their money exists but the systems required to move it do not work?
A banking system that cannot move money is not functioning, however strong its balance sheets may be. That is how an operational incident could become a systemic financial crisis.
This leads to a separate question: the regulators know, but do they know enough? To be fair, regulators have recognised this problem.
The European Union's Digital Operational Resilience Act, DORA, became applicable in January 2025 and introduced requirements covering ICT risk management, incident reporting, resilience testing and third-party technology risk.
The UK has also strengthened its operational resilience regime and, in July 2026, designated four technology companies, including Google Cloud EMEA, as critical third parties to the financial sector.
That is significant because it recognises that some technology companies have become so important to financial stability that regulators must look beyond the banks themselves, but there is a fundamental challenge. Regulating individual banks is one thing. Regulating the infrastructure shared by hundreds or thousands of financial institutions and more – hospitals, airlines, retailers and the government itself – is quite another.
A regulator can demand that a bank demonstrate resilience, maintain recovery plans and test its ability to withstand disruption. Yet what happens when every bank's recovery plan depends on the same technology provider restoring its services?
What happens when the backup provider relies on the same telecommunications network or when the software required to switch systems depends on infrastructure that has also failed?
There is the heart of the issue.
The issue is not whether Google, Microsoft or Amazon operate reliable systems. Generally, they do, and there are compelling reasons why banks use them. The issue is whether the financial system as a whole can survive the failure of infrastructure that everybody has come to depend upon. A thousand resilient banks do not make a resilient financial system if they all depend on the same point of failure and the AI revolution makes this even more dangerous
Banks are racing to become AI-native. They are investing billions in artificial intelligence, automated decision-making, intelligent agents, real-time fraud prevention and systems that increasingly make decisions without human intervention. Where does most of this intelligence live? In the cloud and who provides the computing infrastructure, specialised processors, foundation models and development environments that make this possible? An increasingly concentrated ecosystem of global technology companies.
As banks become more dependent on AI, their exposure extends beyond cloud hosting into models, data pipelines, identity infrastructure and autonomous decision-making systems.
Consider what happens when an AI-powered bank uses one provider for its cloud infrastructure, another for its foundation models and a third for its transaction intelligence, but those services ultimately depend on overlapping technology platforms.
An outage could interrupt not only access to banking applications but also the intelligence required to operate them.
The deeper the automation, the more important the resilience of the infrastructure beneath it.
We are building a financial system that promises to be faster, smarter and more efficient than anything that has existed before, while potentially concentrating more of its operational dependencies in fewer hands.
This is not an argument against AI or cloud computing. Quite the opposite. Both are fundamental to the future of banking.
It is an argument against confusing technological sophistication with systemic resilience.
And then there is a wider question that deserves attention here.
For centuries, banks controlled the infrastructure of finance. They owned the branches, operated the ledgers, managed the payment systems and maintained the relationships that connected businesses and consumers to money.
Today, banks increasingly own the customer relationship while renting the technology infrastructure required to deliver it.
That changes the balance of power.
Google, Amazon and Microsoft are not banks, yet their infrastructure has become critical to banking. Their commercial decisions, technical architectures, investment priorities and operational failures can have consequences across the financial system.
The companies that provide the infrastructure are becoming as important as the institutions that provide the financial services, and this creates a fascinating paradox.
Regulators spent years worrying that a handful of banks controlled too much of the financial system. Now a handful of technology companies operate an increasing share of the infrastructure on which those banks depend.
We have reduced some forms of financial concentration while creating new forms of technological concentration.
The question is whether we have simply moved systemic risk from institutions we understand and regulate extensively to infrastructure whose interdependencies are far harder to see. The answer is not to abandon the cloud or demand that every bank rebuild its own data centres. That would be expensive, inefficient and, in many cases, less resilient than using specialist providers. Nor is multi-cloud automatically the solution. Running across several providers adds cost and complexity, and a bank that cannot switch critical workloads during a crisis has achieved little more than a more expensive dependency.
The answer begins with understanding what actually matters.
Banks need to identify the critical services that customers and markets cannot function without, map every technology dependency supporting those services and establish whether they can continue operating when a major provider fails.
That means testing genuine provider failures rather than simply rehearsing recovery procedures within the same cloud environment.
It means maintaining independently operable alternatives for essential functions where justified, ensuring that customers have practical ways to access money during disruption and understanding which supposedly independent suppliers share the same infrastructure.
Most importantly, it means regulators must examine concentration risk across the financial system rather than relying solely on individual institutions to manage their own exposures.
The question is no longer whether each bank has a disaster recovery plan. It is whether those plans still work when everybody experiences the same disaster.
Yesterday's Google Cloud outage was resolved, although the effects on individual services took time to clear. The financial system did not collapse, and there is no evidence that the incident threatened the solvency of the affected banks, but that is precisely why it matters.
It was a relatively contained infrastructure incident that nevertheless disrupted access to banking services and demonstrated the reach of a shared technology dependency.
Imagine the consequences of something larger.
A cyberattack against a major cloud provider. A prolonged regional power failure. A critical software update that simultaneously disables services across multiple providers. A geopolitical confrontation that interrupts access to essential digital infrastructure.
These are different scenarios with different probabilities, but they expose the same fundamental weakness: concentration of operational dependency.
We spent decades asking whether banks were too big to fail, then built a digital banking system dependent on technology companies whose failure can disrupt multiple banks simultaneously.
And perhaps the greatest irony is that the next financial crisis may not begin with reckless lending, toxic securities or a collapse in asset prices.
It may begin with a perfectly ordinary technical failure in a data centre somewhere outside London.
Because when the infrastructure fails, the banking system stops working.
So here's my question: if your bank cannot operate when Google goes down, who is really running your bank?
Don’t blame it on the sunlight
Don’t blame it on the moonlight
Don’t blame it on the good times
Blame it on the Google
Sources and further reading
- The Telegraph — Google Cloud down: Revolut and other banking apps crash after system outage
- BBC News — Google resolves cloud outage affecting UK banks and websites
- Reuters — Google Cloud services down in UK, banks and public sector report issues
- The Guardian — Too big to not fail: Google outage exposes UK reliance on a handful of cloud providers
- Reuters — Revolut says some services back online after outage
Chris M Skinner
Chris Skinner is best known as an independent commentator on the financial markets through his blog, TheFinanser.com, as author of the bestselling book Digital Bank, and Chair of the European networking forum the Financial Services Club. He has been voted one of the most influential people in banking by The Financial Brand (as well as one of the best blogs), a FinTech Titan (Next Bank), one of the Fintech Leaders you need to follow (City AM, Deluxe and Jax Finance), as well as one of the Top 40 most influential people in financial technology by the Wall Street Journal's Financial News. To learn more click here...