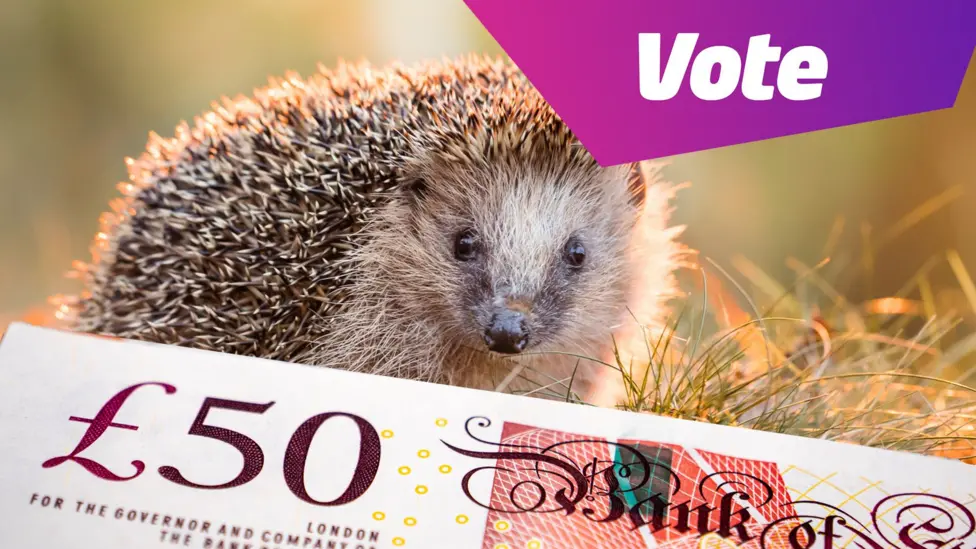
Britain is replacing its heroes with wildlife and, judging by the reaction, you would think the Bank of England has announced that Winston Churchill is being retrospectively defeated by a hedgehog. Out go Jane Austen, JMW Turner and Alan Turing and in comes a barn owl, a bumblebee, a puffin and a hedgehog, although the monarch remains. Apparently, national identity can survive contactless payments but struggles with an insect.
I love cash.
As a numismatist, I see something in coins and banknotes that no banking app can reproduce. They are little pieces of history you can hold in your hand, showing what a country celebrates, who commands its loyalty and what happens when its promises fall apart. A banknote can tell you more about a nation than a minister’s speech, particularly when its denomination runs into the trillions.
That is why I write about this repeatedly.
Back in 2013, I discussed the controversy over replacing Elizabeth Fry with Churchill, which threatened to leave Britain’s banknotes without a historical woman beyond the Queen. The campaign that then helped bring Jane Austen onto the £10 note demonstrates that the pictures matter. Money carries a message as well as a value.
By 2025, when the Bank asks what we want on the next series, I suggested David Bowie, a red squirrel and Stonehenge among the possibilities. So I can hardly declare the arrival of wildlife a national catastrophe when I have already nominated a squirrel. My objection would be stronger if they replaced Alan Turing with Mr Blobby.
The argument against animals is easy to understand.
Historical figures celebrate achievement and invite curiosity. A child asks who Alan Turing is and discovers an extraordinary story about mathematics, computing, war and persecution. The Independent captures the objection in its headline: “No one aspires to be a bee”.
Fair enough, although nobody needs to aspire to be a bee to recognise that the country depends on more than celebrated humans. Wildlife is part of national identity too, and there is something faintly ridiculous about treating a puffin as an attack on civilisation. We can honour human achievement in books, classrooms and museums without requiring the checkout at Tesco to do all the educational work.
The Bank of England’s case for change also involves security and making the denominations distinctive. Almost 500,000 people respond to its wildlife consultation, and the new notes take years to design, test and introduce. This is a planned currency redesign, however enthusiastically we turn it into another culture war.
Yet the real question is who actually uses cash? Looking around a world of cards, phones and watches, the tempting answer is pretty much no-one. We are fighting over the illustrations on money that increasingly stays out of sight.
I was in Marks & Spencer the other day when the card systems failed due to a sudden outage. All the store assistants ran around saying cash only, and all of us looked at each saying who the hell uses cash?
Having said that, there is still a small fan base.
UK Finance reports 3.9 billion cash payments in 2025, representing 8% of all UK payments, compared with 45% in 2015. Around 1.4 million people mainly use cash for everyday spending, while 19 million use it once a month or less. Cash is becoming marginal, but several billion payments make a rather substantial margin.
This distinction matters because the people abandoning cash and the people depending on it often inhabit different financial worlds.
FCA research identifies digital exclusion and low income as the strongest factors associated with cash reliance. For someone managing a tight budget, physical money can make the limits visible in a way that another number on a screen does not.
Of course, the case against cash is powerful.
Businesses have to count it, store it, transport it and protect it. It can be stolen or lost, and anonymous payments make life easier for people who would rather the taxman or police never know what they are doing. Digital payments offer convenience that most of us willingly choose, and I have no desire to queue behind someone searching for the exact change simply to preserve the romance of a banknote.
But anonymity also protects ordinary people.
Buying something without generating another entry in a commercial database is a legitimate preference. We should be careful about building a society in which every financial interaction requires an account, a functioning network and permission from an intermediary. The cash enthusiast and the digital enthusiast both have an argument here, because convenience does not settle every question about freedom.
Cash also offers a useful alternative when digital systems fail, provided people already have some and businesses can accept it. That qualification matters. An empty wallet is no protection against an outage, and a cash machine connected to a failing network cannot perform miracles. Preserving resilience requires a working cash system, rather than an emergency recommendation to find some banknotes after everything stops.
In 2018, I wrote that cash should be in a museum, and I have this conflict between the man who wants to collect such things versus the man who believes they no longer have any utility.
So, yes, changing from heroes to wildlife is a significant cultural choice. Yet the far bigger change is the transfer of our everyday money into systems where access depends on institutions and infrastructure most people barely understand. We scrutinise the face on a £10 note while giving much less attention to the companies standing between us and our digital £10.
I will enjoy collecting the new notes, and I will continue asking whether the people who need them can obtain and spend them. Britain can cope with a bumblebee on its currency. It should worry considerably more about a future in which you have money but somebody else decides whether you can use it.
Chris M Skinner
Chris Skinner is best known as an independent commentator on the financial markets through his blog, TheFinanser.com, as author of the bestselling book Digital Bank, and Chair of the European networking forum the Financial Services Club. He has been voted one of the most influential people in banking by The Financial Brand (as well as one of the best blogs), a FinTech Titan (Next Bank), one of the Fintech Leaders you need to follow (City AM, Deluxe and Jax Finance), as well as one of the Top 40 most influential people in financial technology by the Wall Street Journal's Financial News. To learn more click here...