Last Friday, the United States grounded flights across the country for four hours because of a technical problem during an upgrade to its air traffic control communications infrastructure. More than 15,000 flights were delayed or cancelled, affecting an estimated 1.5 million passengers.
The problem arose while contractors were replacing ageing copper wiring with fibre-optic cables. A router reportedly began flooding other systems, disrupting communications across the aviation network. The precise cause remains under investigation.
The US government is now discussing spending between $30 billion and $50 billion modernising its air traffic control infrastructure.
It is an extraordinary illustration of a problem I've been discussing for years.
Remember the Italian bridge that collapsed? Remember the building of the Elizabeth Line in London?
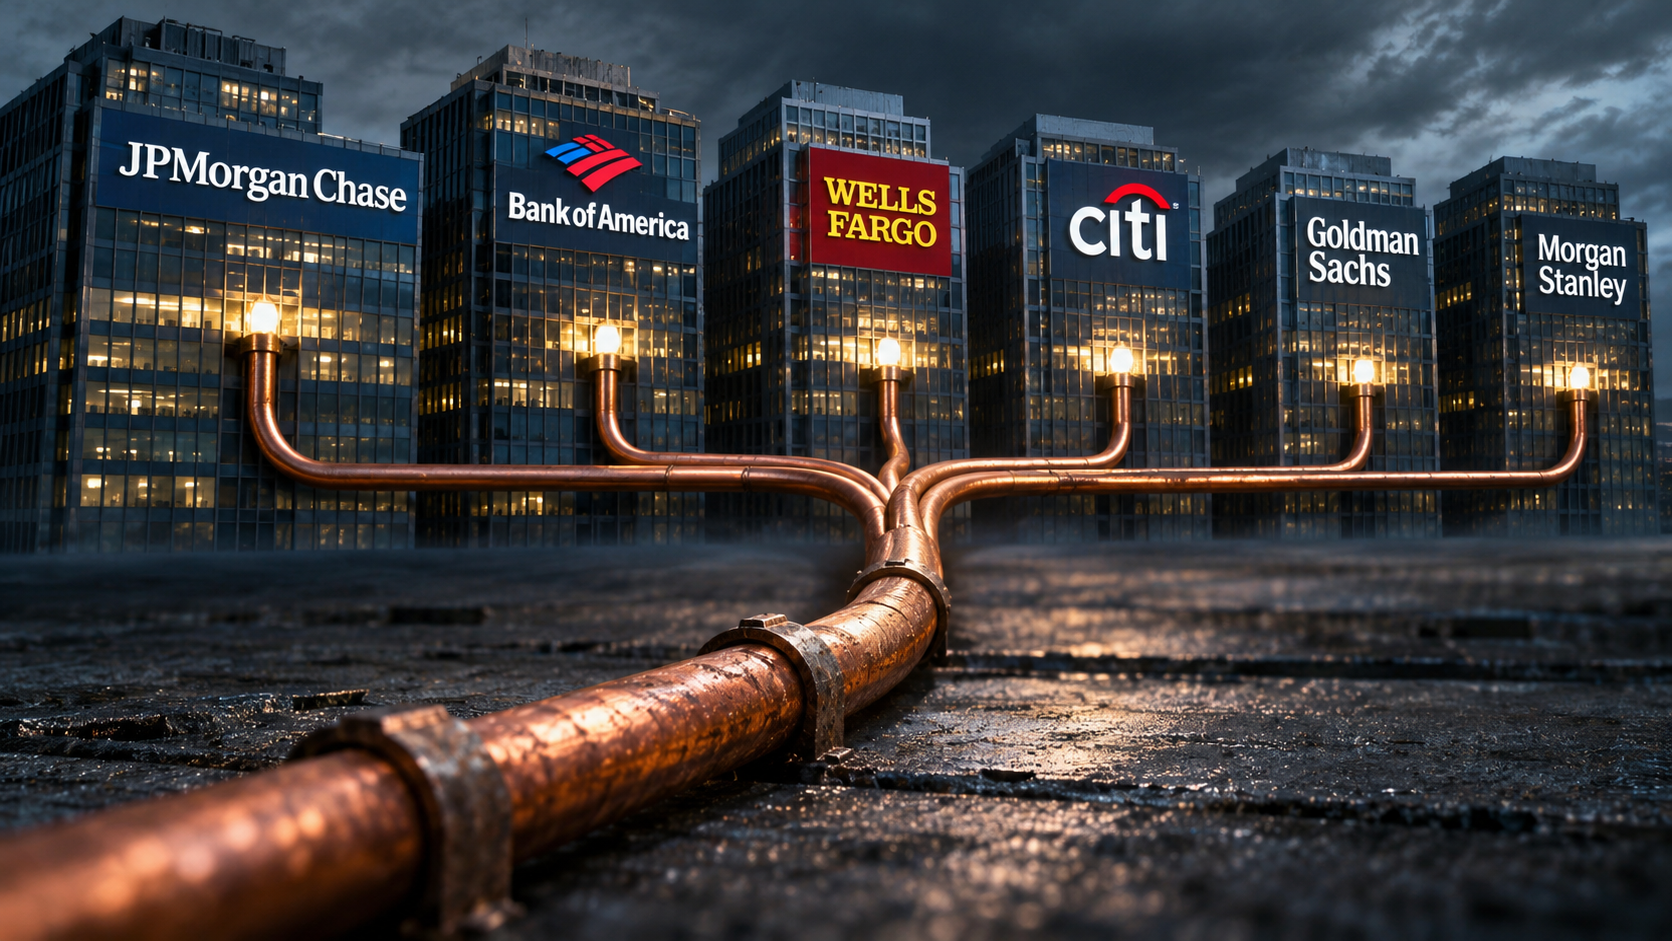
Which brings me to banking and my favourite hobby horse: systems that are half a century old or more, and what happens when the systems we depend upon are so old, so interconnected and so complicated that changing them becomes more dangerous than leaving them alone?
Is banking still running on the equivalent of copper wires at its core, while concentrating its future in the hands of a handful of cloud providers? The latter point I blogged about on Friday after the Microsoft outage but, by coincidence, that was on the same day US airports shut down due to a change of wiring.
It just makes you realise how fragile our world is today because it runs on the technology of yesterday. Many of the world's largest financial institutions still depend on technology whose foundations date back to the 1960s and 1970s. Systems built when the Beatles were topping the charts, the internet didn't exist, and computers occupied entire rooms. Banking systems were built around mainframes, batch processing, magnetic tapes and programming languages such as COBOL.
Many of those foundations are still with us today.
Back in 2017, Reuters reported that 43% of US core banking systems were built using COBOL, a programming language developed in 1959. Almost a decade later, technology companies are still quoting the same figure. In May 2026, Amazon Web Services estimated that more than 40% of banks continued to use COBOL-based core systems, while reporting that 45 of the world's 50 largest banks still relied on mainframe applications for mission-critical operations.
Yet there appears to be no independently verified, up-to-date measurement of how many American banks still depend on COBOL.
I guess the question is whether running on a mainframe with COBOL in the back office is a good or a bad thing. If it ain’t broken, don’t fix it?
The major point here is that if you never challenge, change or replace the systems you depend upon, you eventually become a prisoner of them. Innovation demands change, but changing critical infrastructure demands careful planning, testing and resilience.
Meanwhile, my estimate is that the major US banks collectively spend around $50 billion annually just keeping their existing technology operations running.
Consider JPMorgan Chase, which has a technology budget approaching $20 billion in 2026, with approximately $10.6 billion outside its investment allocation. Bank of America spends around $13 billion annually on technology, with roughly $9 billion outside its spending on new initiatives. Add Citigroup, Wells Fargo and the other major US banks, and the scale of expenditure becomes extraordinary.
Of course, not all of this is legacy maintenance, but it illustrates how much money goes towards running existing systems rather than developing new capabilities.
EY reported in March 2026 that the largest banks devote an average of 58% of their IT budgets to running existing operations, compared with just 12% allocated to strategic change.
Think about that.
For every $100 the largest banks spend on technology, just $12 is allocated to strategic transformation.
That is the problem.
Banks are spending billions keeping yesterday's technology working rather than building tomorrow's banking.
We talk endlessly about artificial intelligence, autonomous finance, tokenisation and quantum computing, yet the foundations of much of our financial system remain rooted in another century. We are building the future of banking on the technology of the past, while entrusting much of that future to a handful of cloud providers.
Is the banking system still running on a copper wire? More importantly, what happens when somebody tries to replace it?
Chris M Skinner
Chris Skinner is best known as an independent commentator on the financial markets through his blog, TheFinanser.com, as author of the bestselling book Digital Bank, and Chair of the European networking forum the Financial Services Club. He has been voted one of the most influential people in banking by The Financial Brand (as well as one of the best blogs), a FinTech Titan (Next Bank), one of the Fintech Leaders you need to follow (City AM, Deluxe and Jax Finance), as well as one of the Top 40 most influential people in financial technology by the Wall Street Journal's Financial News. To learn more click here...